Personal finances are an important part of every individual’s life. March is Credit Education Month and is a good time to better understand what credit is and how it works. This month’s blog will focus on the basics of credit, specifically for young adults, because it’s never too early to start learning about how to manage your credit!
What is Credit?
Simply put, credit is the ability to borrow money or the ability to buy something today and pay for it later. “Borrowing” is when a lender provides money and there is an obligation to pay it back, usually with interest. To determine if you’re approved to borrow money, lenders look at different factors such as your credit history, your credit report, the number of credit cards you have, etc. Credit can be helpful in emergency situations, is more convenient than carrying around cash, and allows you to pay for large purchases over an extended period of time. Credit cards are one of the most common methods of borrowing that people have access to.
Access to Credit
Your credit history indicates how you’ve managed your past and present finances. Many financial institutions use that information to predict your future financial behaviors. If you have a good record of paying bills on time, it will be easier to borrow money. As a young adult, you will begin to make significant life purchases, like a house or a new vehicle. Having a good credit history, or credit score, can determine whether you get approved for:
- Auto Loans
- Apartment or Housing Leases
- Insurance and Utility Contracts
- Credit Cards
- Employment
- Mortgage Loans
How Do You Establish Credit?
Establishing good credit takes time, and the length of your credit history is an important factor in determining your credit score. The sooner you start building your credit, the more time you have to work towards building a good credit score.
One way to start building credit is with a credit card. Many credit card companies offer credit cards tailored to students. Card issuers can include benefits and perks for college students, such as a monetary reward for getting good grades! You must be 18 to sign up for your first credit card independently. It is important to note that you should ensure that you are financially responsible enough to sign up for your first credit card before doing so. Be well informed before you apply! Make sure you:
- Understand how credit cards work, including fees and interest
- Have sufficient income to repay any accumulated debt
- Establish responsible money management habits
- Always pay your bills on time
While getting a credit card as a student is a great way to establish your credit, not paying your bills on time is an easy way to lower your credit score.
What is a Credit Card?
Credit cards are a common form of borrowing money. This means the balance goes up and down as you make purchases and payments.
When using a credit card, you can make purchases conveniently without using cash. All credit cards require you to pay at least a portion of the bill, called the minimum payment, every billing cycle. The billing cycle is typically one month. If you make just the minimum payment, you will have to pay interest in addition to the unpaid balance. However, if the balance owed is paid in full each month, interest is not added.
Tips for Building and Maintaining Credit
How can you tell if you’ve been a victim of cyberattacks?
You must be responsible about what you choose to pay for with your credit card. Instead of making big purchases on your credit card that you truly cannot afford, make smaller purchases that you know you will be able to pay off. You can start by making a few purchases on your credit card each month to begin building a good credit score, as long as you pay off the amount spent.
Consider using your bills to your advantage to build good credit. Use your credit card to pay for bills you pay consistently every month, such as utilities.
Maintain a Dependable Payment History
Payment history makes up 35% of your credit score calculation. Missing a payment or making less than the minimum payment on your bill will cause a significant decrease in your credit score. On-time payments prove that you’re creditworthy. You can set up a recurring notification to pay your credit card bill to avoid late payments.
Avoid Opening Too Many Accounts
The more credit cards you have, the more at risk you are of overspending and getting behind on your payments, which results in more debt. You should keep a primary card to use for spending when necessary. If needed, have an additional credit card as a backup. Some cards even have specific rewards programs that provide you with great benefits when used correctly.
Understanding Credit Scores
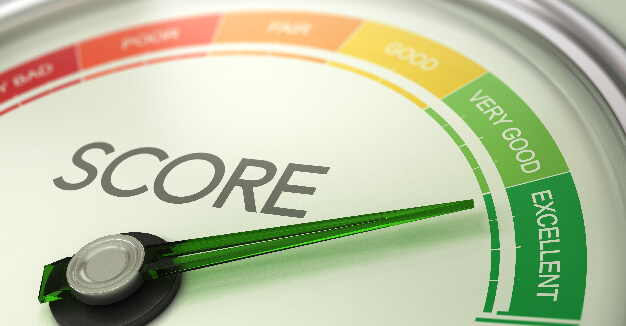
A credit score typically ranges from 300 to 850
| 300 – 579 | Poor |
| 580 – 669 | Fair |
| 670 – 739 | Good |
| 740 – 799 | Very Good |
| 800 + | Excellent |
There are a few factors that influence credit scoring and that determine the overall calculation.
- Payment History
- Amount Owed
- Length of Credit History
- New credit
- Credit Mix
- Number of Credit Inquiries
Individuals with higher credit scores are usually a lower risk to creditors. Establishing good credit starts at an early age. Set yourself up for success by being financially responsible enough to apply for a credit card; maintain a solid credit history, make payments on time, and continually educate yourself on money management.
If you have any questions or want to learn more about credit education, please contact our banking professionals at Wallis Bank!
- Ⓒ Wallis Bank, All rights reserved.
-
 Equal Housing Lender

- Privacy Notice Disclosures